Contents of this article
One of the biggest financial mistakes is failing to make a clear retirement plan while you are young. The word “retirement” often sounds frightening because it is associated with old age and boredom, yet it is the moment you complete a cycle of hard work and get to pursue all your colorful interests.
Defining Your Problem
Let’s assume you are at one of the different stages of your working life: just starting work, about to get a job, or already halfway through a hard-working career.
Whatever your situation, one common life goal is to make sure you will have a happy and fulfilling life. So retirement should not become a barrier that stops us from living the life we want. We should keep aiming for the lifestyle we feel we deserve.
If that is true, it implies that you need the same disposable income as when you were working. Less disposable income will cause us problems after retirement.

Let me use some numbers to make this clearer:
Suppose you will work continuously for the next 25 years (your earning years) and then retire. After retiring, you may live for another 20 years. Suppose also that the cash you need today to maintain your lifestyle is VND 20,000,000 a month.
The idea is that after 25 years, for the next 20 years of retired life, you will still need VND 20,000,000 a month, or about VND 240,000,000 a year, to maintain your lifestyle.

I’m sure you will all agree that this is a real-life problem that all of us need to solve.
There are two questions:
- How much money do you need to have saved by the time you retire, that is, by 2047?
- How do you build up that amount?
Some people may jump straight to an answer with a few simple calculations:
It is VND 240,000,000 a year (VND 20,000,000 a month for 12 months), and over 20 years that is (240,000,000 * 20) = VND 4,800,000,000.
So if we build a retirement fund of VND 4,800,000,000 by 2047, we can easily get through the next 20 years of retired life spending VND 20,000,000 a month, until 2066.
If only life were that simple!
Remember our 2 earlier lessons on compound interest and the time value of money.
Inflation and Life’s Other Complications
Without inflation, the answer above would be exactly right: in 2047, VND 4,800,000,000 would carry us comfortably through our retirement years, spending VND 20,000,000 a month until 2066 on electricity, water and plenty of other purchases.
But inflation always exists, and it complicates life in many ways. Inflation is what makes everything more expensive. For example, a bowl of pho might cost VND 50,000 today but VND 60,000 next year (wheat prices rose more than 40% in just the first week of the 2022 Russia–Ukraine war). This price increase is the effect of a concept called inflation; in other words, the purchasing power of money has fallen over the past year or so.
This always holds true: money today will always be worth less at some date in the future. It means that VND 20,000,000 today will not be worth VND 20,000,000 tomorrow; its value naturally declines because of inflation. For that reason, we cannot simply multiply the amount needed by the number of years and arrive at a neat VND 4,800,000,000 as above
The Future Value of Your Retirement Fund
To find the amount we really need, we have to work out what VND 20,000,000 today will be worth in 25 years. This is where we use what we learned in the lesson The Time Value of Money.
To go further and estimate the figure needed at the start of retirement, in 2047, you need a view on long-term inflation.
We will assume average inflation of about 5% a year. The question now is: with 5% inflation, what will VND 240,000,000 be worth 25 years from now?
If you recall the Time Value of Money lesson, we learned how to calculate future value. Once we have all the future values, we add them up to get the total amount we need to have saved at the start of retirement.
I will do this for the first 2 years and then let MS Excel calculate the rest.
From the previous chapter, the future value formula is:
Future value = P * (1 + R) ^ n
Where,
- P = the principal, i.e. 240,000,000
- R = the opportunity cost, which in this context is the inflation rate, so 5%
- n = the number of periods, 25 in this case
Substituting these values:
240,000,000 * (1 + 5%) ^ 25 = 940,830,993
So in 25 years, having VND 940,830,993 will be worth the same as having VND 240,000,000 today.
For the 2nd year:
240,000,000 * (1 + 5%) ^ 26 = VND 987,872,543
So in 26 years, having VND 987,872,543 will be as good as having VND 240,000,000 today.
…
Keep repeating these steps and you will end up with an Excel table for your retirement plan. Here, with 5% inflation, I will show you how much money you need for a secure retirement:
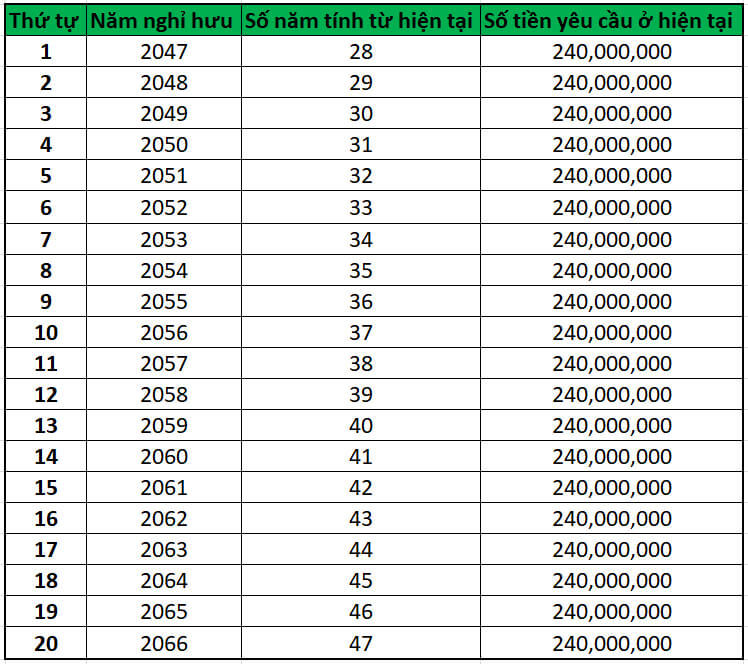

A few things have been simplified here. For example, a constant monthly requirement of 20,000,000 may not be accurate. As we get older, we would rather sit at home sipping a cup of tea than go out to the city’s smart, trendy venues. We may skip eating out or going to the cinema, and we don’t need to buy expensive clothes as we did when we were young.
Our needs may be very different, and from what I have observed and understood, older people usually need less money to live on than younger people. So you may not need 20,000,000 a month when you retire.
However, this is an article about a personal finance problem, so it is best to take a conservative approach and focus on the idea rather than the detailed numbers.
In the next chapter, we will tackle the second, harder half of the problem: how do you build this retirement fund?
Happy Trading !
“Stock Trading For A Living” Course
Green Chart designed this course to build a solid foundation in fundamental analysis & stock valuation (Fundamental Analysis), while showing students how to integrate it effectively into their existing trading system, especially for traders who already use technical analysis (Technical Analysis). The program includes 5 theory sessions and 6 months of hands-on trading guidance in the live market with the instructor.
See full course details here.