Contents of this article
When looking at a company’s business results, the first figure most stock investors check is net profit, also called profit after tax. It is the clearest figure for assessing a company’s performance. From there, EPS, or earnings per share, is used to assess the company’s profitability by comparing it with its own history and with other companies in the same industry.
What is EPS?
What is EPS? How do you calculate EPS?
EPS (earnings per share) is the profit after tax attributable to each share of common stock held by shareholders, after deducting the claims of preferred stock (preferred dividends) or adjusting for convertible securities (such as convertible bonds) that can be converted into common stock.
Example: Vinh Hoan Corporation (HOSE: VHC) has about 182 million shares outstanding. In 2021, the company’s profit after tax was VND 1,123 billion. If all 182 million shares are common stock, VHC’s EPS is just over VND 6,000 per share. This means that for each common share, VHC generates a profit of about VND 6,000 a year.
The example above illustrates how to calculate EPS in the simplest case, i.e. when the company’s capital structure consists only of common stock (a simple capital structure).
In practice, capital structures are often much more complex, with various securities such as preferred stock, convertible securities, stock options, stock warrants or ESOP shares; the company then has what is called a complex capital structure. These differences in capital structure lead to the 2 common methods of calculating EPS today: basic EPS and diluted EPS.
How to calculate EPS
Basic EPS refers to earnings per share when all of the company’s shares outstanding are common stock.
Basic EPS = (Profit after tax – Preferred dividends) / Weighted average number of shares outstanding
Diluted EPS, meanwhile, considers the case where securities that can be converted into common stock are actually converted. For a company with a complex capital structure, converting these securities affects both the profit available to common shareholders and the total number of common shares outstanding. This can make the new EPS smaller than basic EPS, a phenomenon called dilution. The formula is:
Diluted EPS = (Profit after tax – Preferred dividends) / (Shares outstanding + Shares to be issued on conversion)
Looking at each type of convertible security separately: if the new EPS after conversion is smaller than basic EPS, the security is called dilutive. Conversely, if the new EPS is larger than the old EPS, it is called anti-dilutive.
To calculate EPS, then, we need the following basic inputs:
- Profit after tax:
For this, we use data from the company’s income statement (profit and loss statement, P&L). The principle is simple: profit after tax is revenue minus all costs (operating costs, depreciation, interest and tax).

- Preferred dividends:
This is the return per share paid to preferred shareholders. It is usually fixed in advance by the company as a commitment to its preferred shareholders. Although these shareholders have priority on profits, their voting rights are restricted on important company matters that require shareholder approval (such as the general meeting of shareholders).
- Shares outstanding:
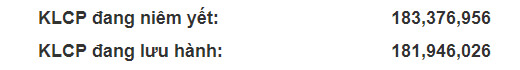
We usually use the weighted average number of shares outstanding at the time of calculation to get the most accurate EPS. Data on shares outstanding can be found on stock websites such as Cafef and Vietstock.
What does EPS tell you?
In theory, EPS gives investors a miniature picture of a company’s profit. Looking at EPS alone is not very meaningful, however; investors should combine it with other financial data to assess a company. Investors usually assess a company’s EPS over time (how it has changed historically) or compare it with industry competitors.
EPS becomes even more important when it is used to value stocks through the P/E ratio. In this article I will only mention this use, and will devote a separate article to the P/E valuation method to give you a clearer picture of the relationship between P/E and EPS.
The limitations of EPS
Although widely used by investors, EPS has some limitations:
First, EPS can be negative (when the company makes a loss), which makes P/E meaningless.
Second, because the inputs for EPS come from the company’s accounting records, EPS can be completely misleading if the books are cooked. The most notorious example of this is Truong Thanh Wood Industry Group (HOSE: TTF) in 2015–2016.
In addition, when a company has a complex capital structure and frequently issues convertible bonds or shares, EPS changes accordingly, which makes calculations difficult and creates unpredictable risks for investors.
Overall, EPS is a fairly important and useful ratio for investors analysing a stock. However, analysis should go deeper and cover more aspects of the business, so investors should look at EPS together with other metrics to make the most informed investment decision.
Happy trading!
The “Stock Trading For A Living” course
Green Chart designed this course to give students a solid foundation in fundamental analysis & stock valuation (Fundamental Analysis), and to show them how to integrate it effectively into their existing trading system, especially for traders who already use technical analysis (Technical Analysis). The program consists of 5 theory sessions and 6 months of hands-on guided trading in the live market with the lecturer.
See full details of the course here.