Contents of this article
One of the most important concepts in the study of options is the option Greeks. The option Greeks describe the factors that affect an options contract and its premium, factors that directly affect a trader’s profit.

The option Greeks are:
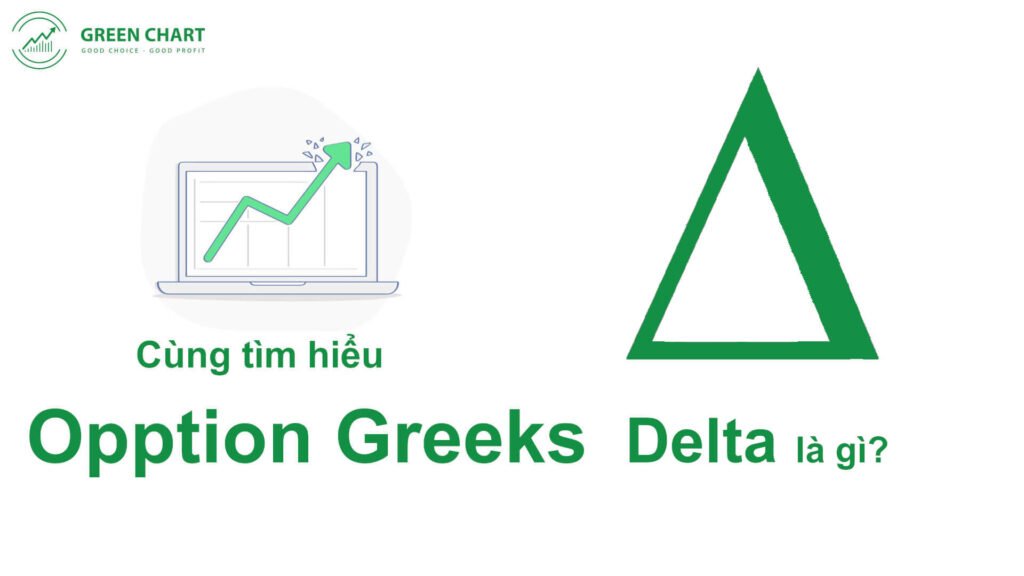
- Delta: measures the change in the option premium for a one-unit change in the price of the underlying asset. In other words, when the underlying price changes by one unit, how many units the premium rises or falls.
- Gamma: measures the change in delta for a one-unit change in the price of the underlying asset.
- Theta: measures the effect of time on the option premium.
- Vega: measures sensitivity to the volatility of the underlying asset; the higher the vega, the higher the option premium
Option delta
Let us take the example of a NIFTY options contract on a foreign market at 9:18 a.m. (this product is not yet available in Vietnam), where the underlying price is 8292, the strike price is 8250 and the option premium is 144.

A NIFTY options contract on a foreign market at 9:18 a.m. (this product is not yet available in Vietnam): the underlying price is 8292, the strike price is 8250 and the option premium is 144.
The next screenshot, at 10:00: the underlying price is 8315, the strike price is 8250 and the option premium is 149.4

The next screenshot, at 10:00: the underlying price is 8315, the strike price is 8250 and the option premium is 149.4
The next screenshot, at 10:55: the underlying price has fallen to 8288, and the option premium has fallen accordingly to 133.45.

The next screenshot, at 10:55: the underlying price has fallen to 8288, and the option premium has fallen accordingly to 133.45.
From these observations, we can see that when the price of the underlying asset (the spot price) changes, the option premium changes too. Put simply, for a call option, when the spot price rises and the strike price stays the same, the premium rises, and vice versa. For a put option, when the spot price rises and the strike price stays the same, the premium falls, and vice versa.
The measure of how much the option premium changes for a one-unit change in the spot price (the underlying price) is delta.
Properties of delta:
- For call options, delta ranges from 0 to 1; some traders use a scale of 0 to 100.
- For put options, delta ranges from -1 to 0; some traders use a scale of -100 to 0.
Delta of a call option
As defined above, delta takes values from 0 to 1, or from 0 to 100. So what does a delta of 0.3, or 30, mean?
Delta is defined as the rate of change of the option premium for a one-unit change in the underlying price. A delta of 0.3 therefore means that when the asset price changes by one unit, the premium changes by 0.3 units.
Continuing the example above: at 10:55 a.m., NIFTY @ 8288; the strike price is 8250; the premium is 133; delta is +0.55.
Suppose that by 3:15 p.m. the underlying rises from 8288 to 8310, a gain of 22 points. The premium will then rise by 22*0.55 = 12.1 units, so the new premium is the 10:55 a.m. premium plus 12.1: 133 + 12.1 = 145.1.
If instead the underlying falls from 8288 to 8200 by 3:15 p.m., the same calculation applies: the underlying falls 88 units, so the premium falls by 88*0.55 = 48.4. The new premium will therefore be 133 – 48.4 = 84.6.
Delta helps us decide which call option to choose. Suppose you expect NIFTY to rise 100 points, so you decide to buy a NIFTY call. You have two choices: call 1 has a delta of 0.05 and call 2 has a delta of 0.2. Which would you pick?
The answer is call 2, with a delta of 0.2. If you expect the underlying to rise 100 points, the premium of option 2 will rise by 20 points, while the premium of option 1 will rise by only 5 points. Option 2 is therefore worth more than option 1 if the underlying rises 100 points as expected, so right now you would choose option 2.
Have you wondered why the delta of a call option lies between 0 and 1?
Case 1: suppose delta is greater than 1
NIFTY @ 10:55 a.m. is 8288; the strike price is 8250; the premium is 133; the option’s delta is 1.5.
NIFTY @ 3:15 p.m. is expected to be 8310. That means the underlying NIFTY has risen from 8288 to 8310, a gain of 22 units. The premium would rise by 22*1.5 = 33 units.
Do you see something odd here? The underlying rises by only 22 units, yet you would have to pay 33 units of premium to insure against a 22-unit rise; at that point the call option makes no sense.
Case 2: suppose delta is less than 0
NIFTY @ 11:00 a.m. is 8288; the strike price is 8300; the premium is 9; the option’s delta is -0.2.
NIFTY @ 3:20 p.m. is expected to be 8200. That means the underlying NIFTY has fallen from 8288 to 8200, a drop of 88 units. With a delta of -0.2, the premium would change by 88*(-0.2) = -17.6. The premium would then be 9 – 17.6 = -8.6. That is impossible, because an option premium can never be negative. So the delta of a call option cannot be less than 0.
What determines the value of delta
Delta is one of the outputs of the Black & Scholes pricing model.
The output of the pricing model is as follows:

Delta of a put option
The delta of a put option lies between -1 and 0. When the value of the underlying rises, the premium falls.
Consider this example: NIFTY’s spot value is 8268; the strike price is 8300; the put premium is 128; delta is -0.55.
Case 1: NIFTY is expected to rise to 8310.
The underlying rises 42 units, so the premium changes by -0.55*42 = -23.1. The put premium is then 128 – 23.1 = 104.9
Case 2: NIFTY is expected to fall to 8230.
The underlying falls 38 units, so the premium rises by (-0.55)*(-38) = 20.9. The put premium is then 128 + 20.9 = 148.9.
Key takeaways on delta:
- The option Greeks affect the option premium
- Call options have a delta from 0 to 1 (or 0 to 100)
- Put options have a delta from -1 to 0 (or -100 to 0)
- A negative delta for puts shows that the underlying price and the premium move in opposite directions.
- A positive delta for calls shows that the underlying price and the premium move in the same direction.
- ATM (at the money) options have a delta of 0.5
- ITM (in the money) options have a delta of |0.5 – 1|
- OTM (out of the money) options have a delta of roughly |0 – 0.5|.
Delta & the underlying price
To clarify how delta behaves when an option is ATM, ITM or OTM, consider the following example:
Suppose NIFTY is trading at 8312 on the spot market and the call strike price is 8400,
- The call is OTM because the spot price is below the strike price. Delta will be between 0 and 0.5; say 0.4
- If the spot price rises from 8312 to 8400, exactly the strike price, the call is now ATM and delta will be about 0.5.
- If the spot price rises from 8312 to 8500, above the 8400 strike, the call at 8400 now works in our favour: it is ITM and delta approaches 1; say 0.8.
- If, after rising to 8500, the spot price then falls back to 8300, the call moves from ITM back to OTM, and delta falls from 0.8; say to 0.3.
What do you notice from this example?
When the spot price changes, the premium changes and so does delta. Delta is not a fixed variable.
Below is a chart showing how delta moves with the spot price for call and put options.

Chart showing how delta moves with the spot price for call and put options.
Look at the blue curve, which shows the delta of a call option. From left to right, the spot value of the underlying rises, meaning the call moves from OTM to ATM and then ITM (the higher the spot price, the more profitable it is to exercise the call). As the underlying price rises, delta rises with it.
The red curve shows the same for the delta of a put option.
How fast delta changes
Next comes the question: which call option should we choose? OTM, ATM or ITM? ITM calls might seem to have the edge, but the story is not that simple. Some traders prefer OTM calls to ATM and ITM calls. Why? Let us look at the examples below.
Studying how fast delta changes.

Delta accelerates through four stages.
- Predevelopment: the option is OTM or deep OTM and delta is close to 0. For example, the spot price is 8400 and the strike is 8700 (an OTM option), with a delta of 0.05. If the spot price now rises from 8400 to 8500, the option is still OTM because 8500 is well below 8700, and delta is still close to 0. If the premium at a spot price of 8400 is 12, then when the spot rises 100 units (from 8400 to 8500) the premium rises to 12 + 0.05*100 = 17. The premium has risen 41.67%.
=> Deep OTM options can offer good returns if the spot price makes a large move.
- Take-off & acceleration: this is the stage where the option moves from OTM to ATM. It offers the best returns and also the most risk.
For example, NIFTY spot @ 8400, call strike 8500 (still OTM, but less so than the 8700 strike), premium 20, delta 0.25. If the spot rises from 8400 to 8500 (up 100 points), the option is now ATM. The premium rises to 0.25*100 + 20 = 45. The premium has risen 125%.
Do you see it? For the same 100-point rise in the spot price, OTM options behave very differently.
=> Slightly OTM options, which typically have a delta of 0.2 or 0.3, are more sensitive than deep OTM options. Slightly OTM options also cost more than deep OTM ones. Traders often consider slightly OTM options.
Now consider an ATM option: the spot price is 8400, the strike is 8400, the premium is 60 and delta is 0.5. When the price moves 100 points, the premium rises to 60 + 0.5*100 = 110. The premium has risen 83%.
=> Investors can buy ATM options when they want to play it safe. ATM options respond even to small price changes. ATM options are more expensive than OTM options.
- Stabilization: the option now moves from ATM to ITM and deep ITM, and delta stabilizes at 1.
For example, NIFTY spot @ 8400,
Option 1: strike @ 8300, ITM, delta 0.8 and premium 105.
Option 2: strike @ 8200, deep ITM, delta 1 and premium 210.
Consider a 100-point move in the spot price: NIFTY rises to 8500.
Option 1’s premium becomes 105 + 0.8*100 = 185; the premium rises 76.19%
Option 2’s premium becomes 210 + 1*100 = 310; the premium rises 47.6%.
=> ITM options are more sensitive than deep ITM options.
To sum up the stages of delta acceleration, let us study the following example:

Summary of the stages of delta acceleration
Consider deep OTM, slightly OTM, ATM, slightly ITM and deep ITM options with strike prices of 2400, 2275, 2210, 2200 and 2150 respectively, each with its corresponding delta. Suppose the price moves 30 points. The premiums change by 50%, 129%, 125%, 95.45% and 40% respectively. Slightly OTM and ATM options are therefore the most sensitive to changes in the underlying price.
Combining deltas
An ATM option has a delta of 0.5, so we know that for every one-unit change in the spot price the premium changes by 0.5 units. In other words, holding one ATM option is like holding half a futures contract. Holding two ATM options is therefore like holding one futures contract: the delta of two ATM options is 0.5 plus 0.5, which equals 1.
Consider an example with three call options

Example with three call options
A long position in these three calls has a total delta of 0.7 + 0.5 + 0.05 = 1.25
Consider an example combining both calls and puts

Example combining both calls and puts
A long position in three calls and one put gives a total delta of 0.25
Technical Analysis course – CMT Level 1
Green Chart designed this course specifically for candidates who want to study and prepare for the CMT Level I exam in Vietnam. The programme includes 27 sessions of theory, practice questions and mock exams. Students also receive free course materials, question banks and mock exams for their exam preparation, plus free lifetime retakes of the course.
Find out more about the course here.
Happy trading!